Basis below cost
Purchased from the developer for less than was spent to build it, despite it being built without a market third-party general contractor margin.
01 / 13
Direct Equity SourceMalakoff, Texas · Target closing December 21, 2026
Not through a fund. Not through a REIT. Directly, in a 430-space Class A facility purchased below replacement cost.
This contains privileged and confidential information and unauthorized use of this information in any manner is strictly prohibited. It is for informational purposes and is not intended to be a general solicitation or a securities offering of any kind. The information contained herein is from sources believed to be reliable, however no representation by Direct Equity Source (DES), Journey.Direct (JD) or Journey.Storage (JS), either expressed or implied, is made as to the accuracy of any information on this property and all investors should conduct their own research to determine the accuracy of any statements made. None of DES, JD or JS, nor their representatives, officers, employees, affiliates, sub-contractors or vendors provide tax, legal or investment advice. Nothing in this document is intended to be or should be construed as such advice. The SEC has not passed upon the merits of or given its approval to the securities, the terms of the offering, or the accuracy or completeness of any offering materials.
Potential investors and other readers are cautioned that forward-looking statements are predictions only, based on current information, assumptions and expectations that are inherently subject to risks and uncertainties that could cause future events or results to differ materially from those set forth or implied. These statements can be identified by terms such as "may", "will", "seek", "should", "expect", "anticipate", "project", "estimate", "intend", "continue" or "believe", or the negatives thereof. This document contains several future financial projections and forecasts. These estimated projections are based on numerous assumptions and hypothetical scenarios and DES, JD and JS explicitly make no representation or warranty of any kind with respect to any financial projection or forecast.
Past performance does not guarantee future results. Current performance may be lower or higher than the performance data presented. All return examples provided are based on assumptions and expectations in light of currently available information, industry trends and comparisons to competitors' financials. Actual performance may, and most likely will, substantially differ from these projections and are provided as illustrations only. DES, JD and JS make no representations or warranties that any investor will, or is likely to, achieve profits similar to those shown herein.

Malakoff, Texas
Privileged & Confidential · Q4 2026
Most storage offerings ask you to underwrite a story. This one asks you to underwrite a building that already exists, a price that is already set, and an operator with a repeatable playbook for filling it.
Purchased from the developer for less than was spent to build it, despite it being built without a market third-party general contractor margin.
With experience leasing up from zero twenty times over, a brand new property is familiar ground, not a first attempt.
With national deliveries projected to fall from 1,205 facilities in 2023 to 455 by 2029, new competitors in this market are less and less likely.
Fast online rentals, seamless self service move-ins, convenient smart entry and access. Systems handle everything that doesn’t require empathy. Humans handle everything that does.
The sponsor’s Manager entity co-invests 10% of the equity alongside investors, on the same terms. The sponsor signs on the debt and is paid a promote only after your preferred return is paid.
Found off-market and bought directly from the developer. No broker, no competitive process. A newly built climate-controlled and drive-up facility on 5.37 acres near Cedar Creek Lake, acquired below what it cost to build.
One of the developers is a general contractor, so the facility was built without a third-party construction margin. We are buying below even that number. Anyone building the same 69,950 square feet of storage today, through a normal GC, would carry the margin on top.
All-in basis including fees, closing, reserves, technology upgrades and retrofitting: $99 per storage SF.
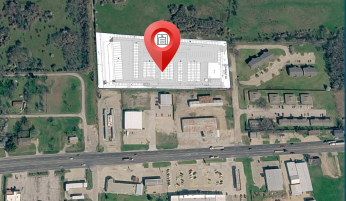
Site · 205 Sunset
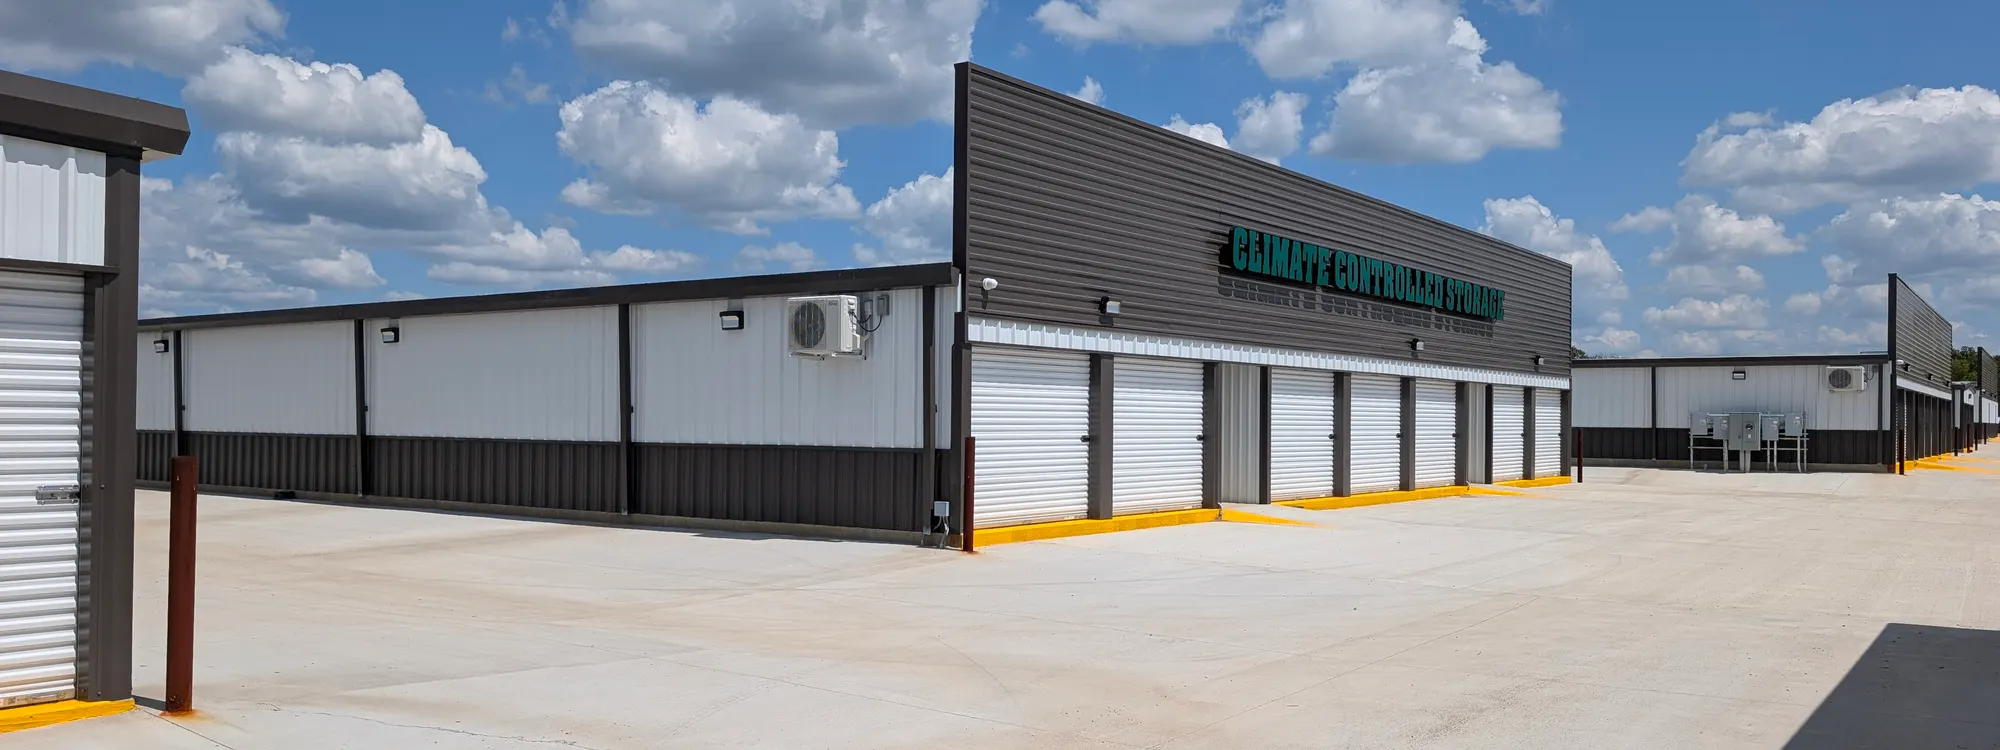
The facility
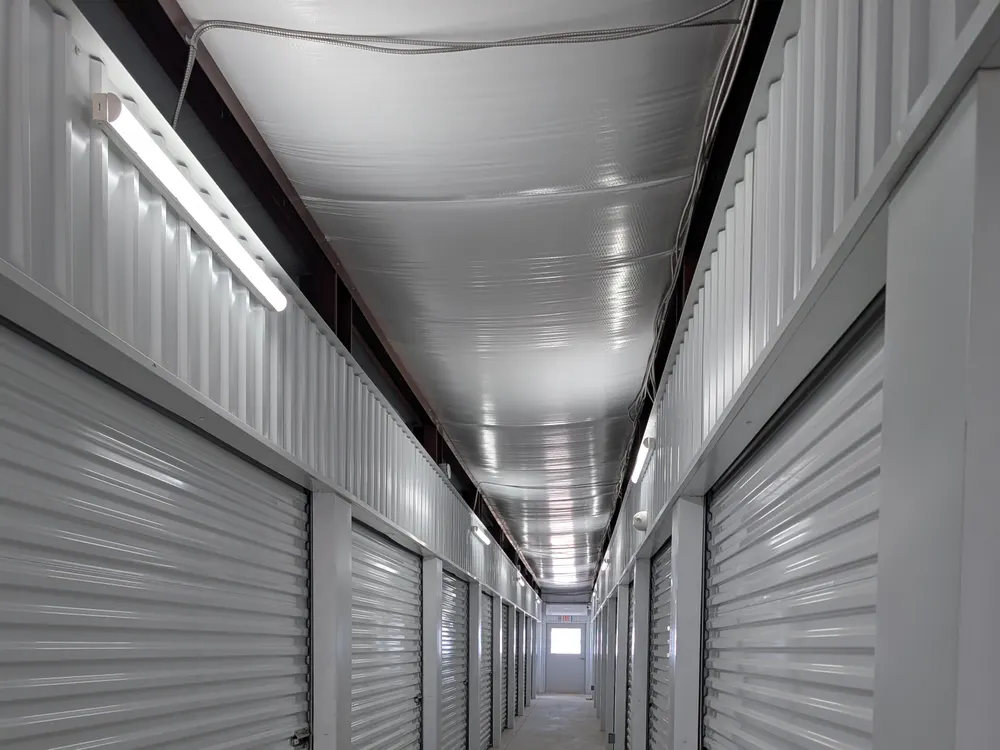
Climate-controlled interior
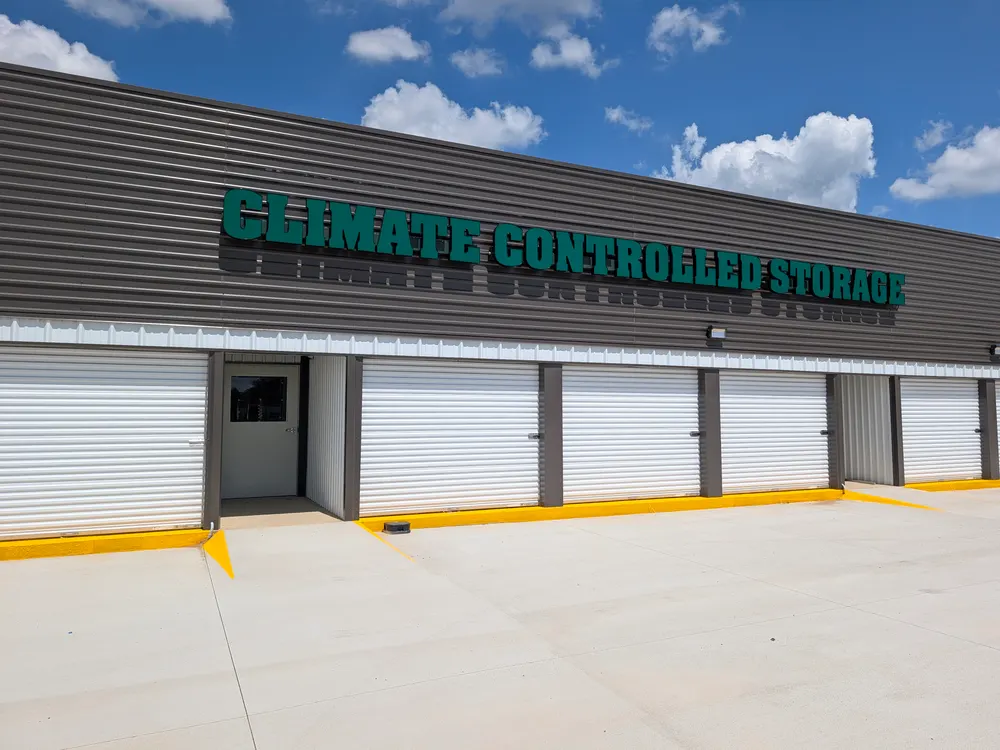
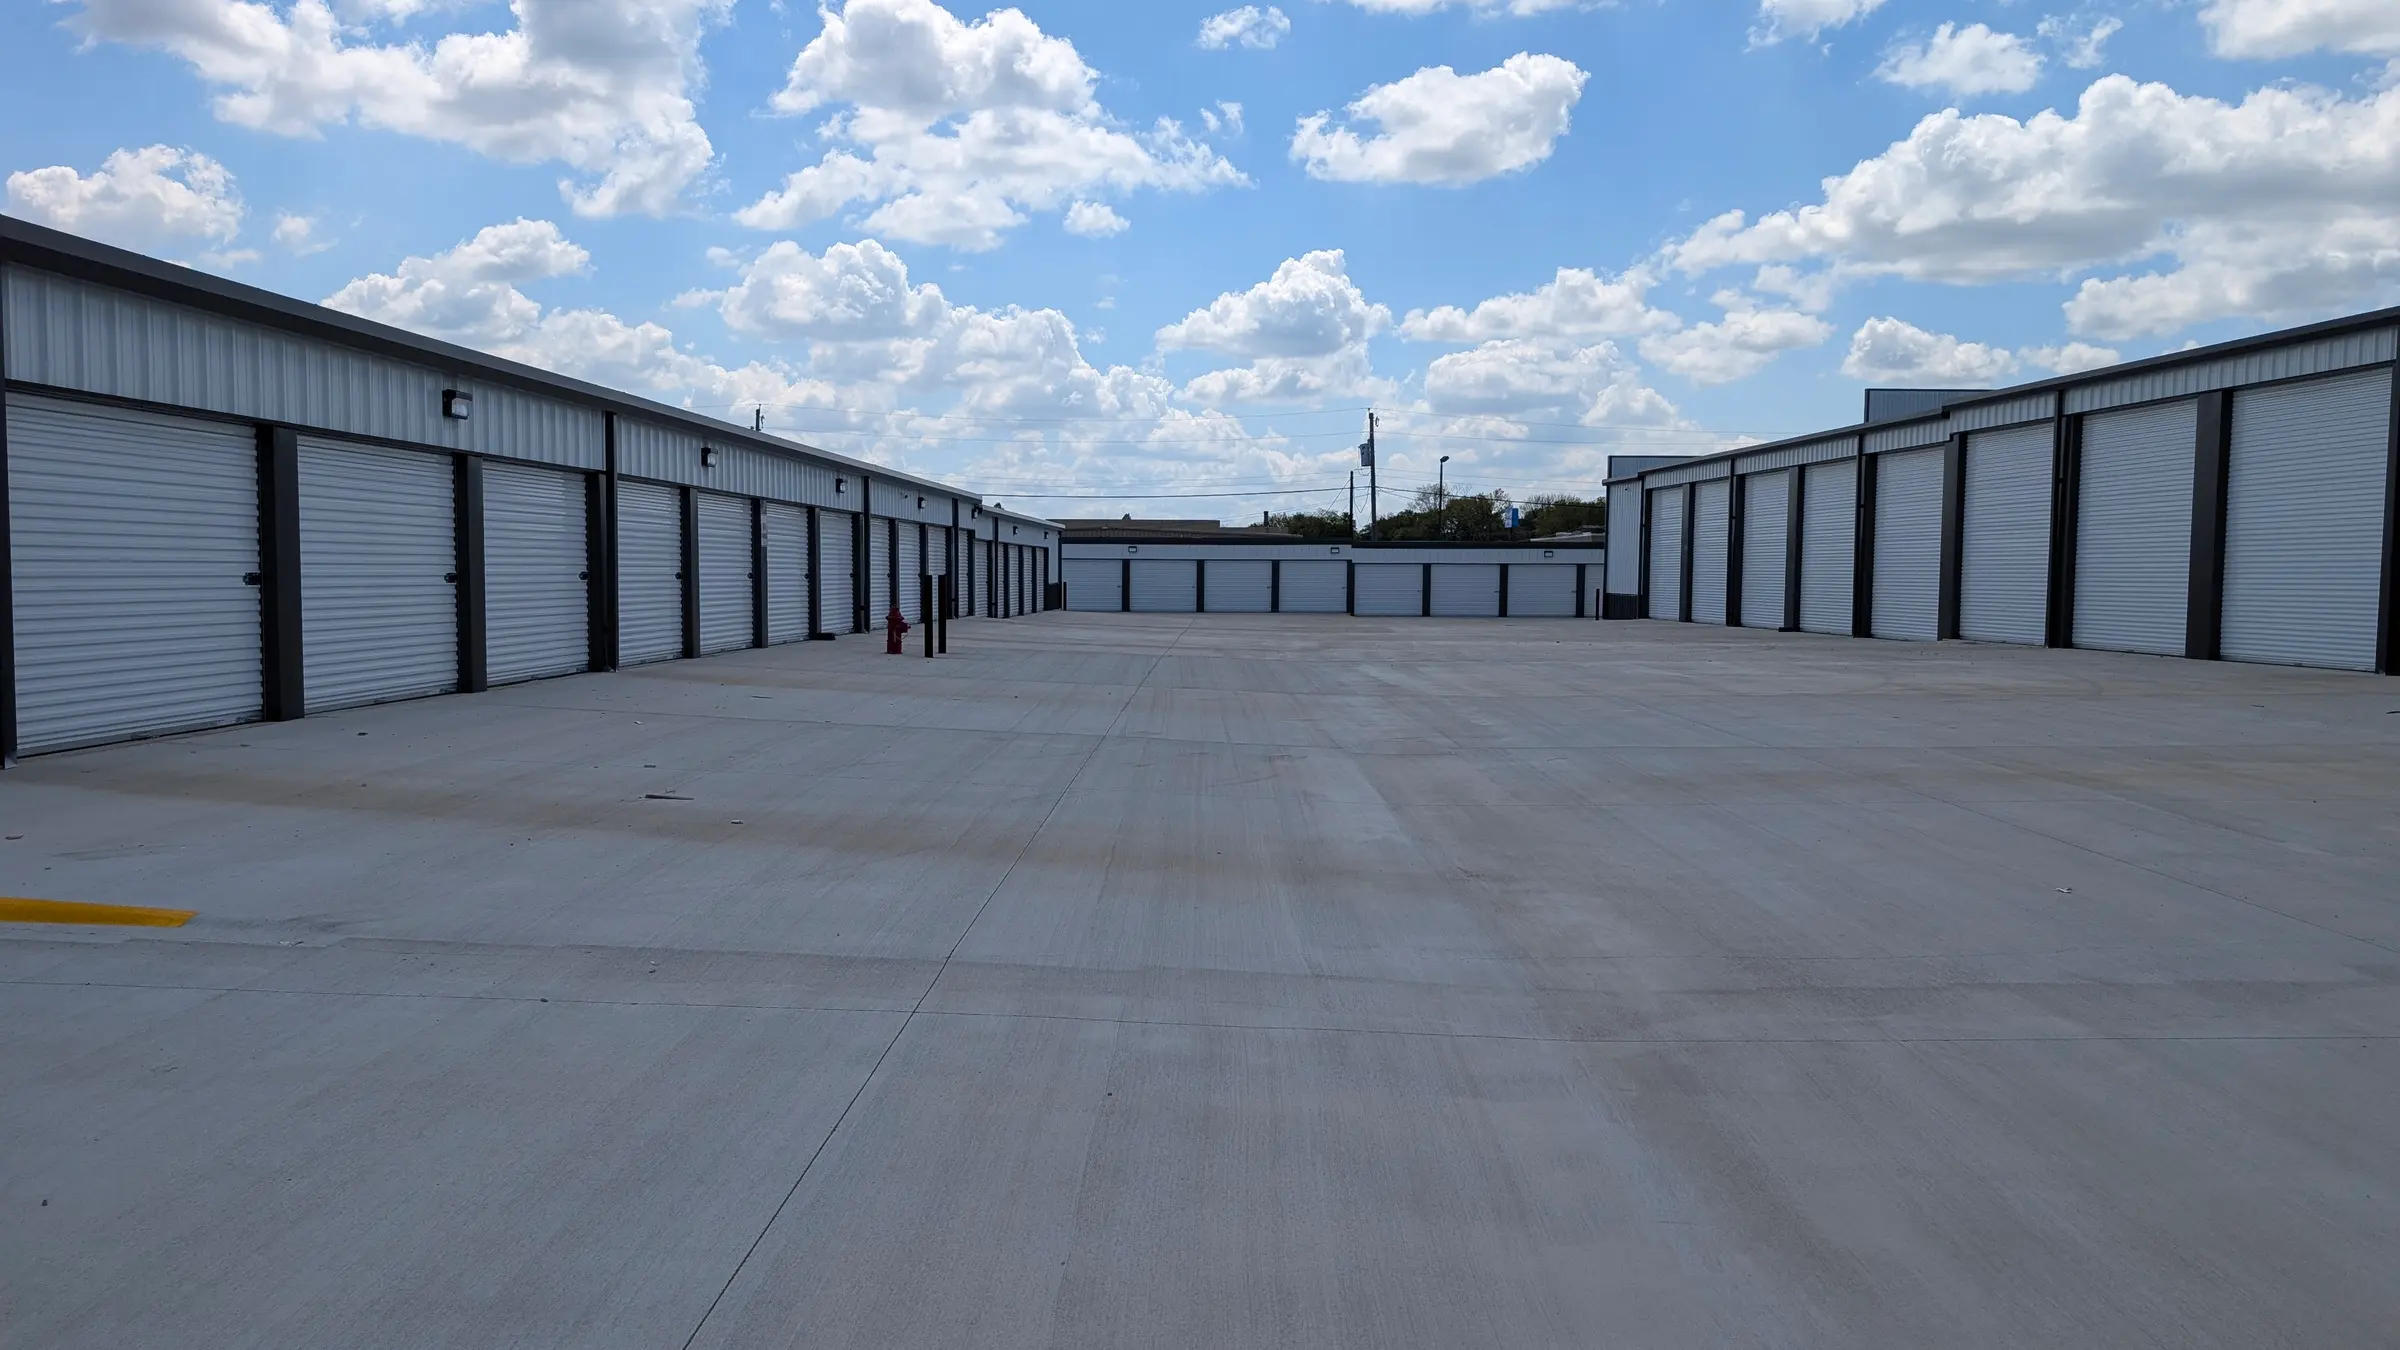
Climate buildingA finished, code-compliant, Class A facility with the expensive part already done: entitlement, construction, utilities, gates and roads. The remaining work is leasing, revenue management, technology upgrades and stellar operations, which is what Journey does best.
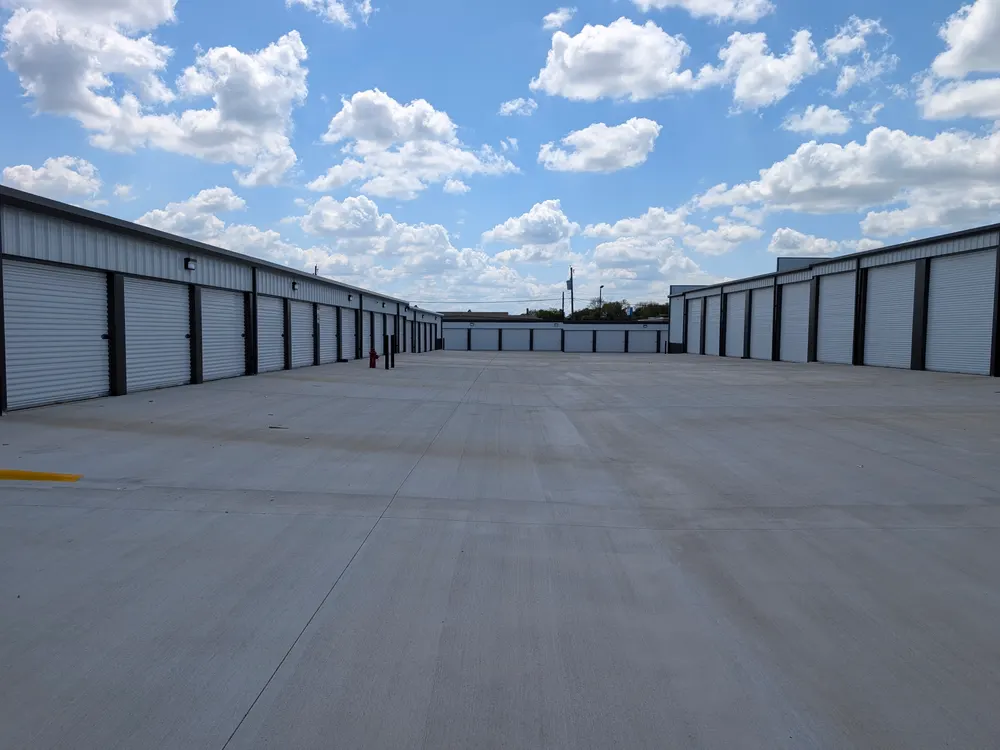
Drive aisle
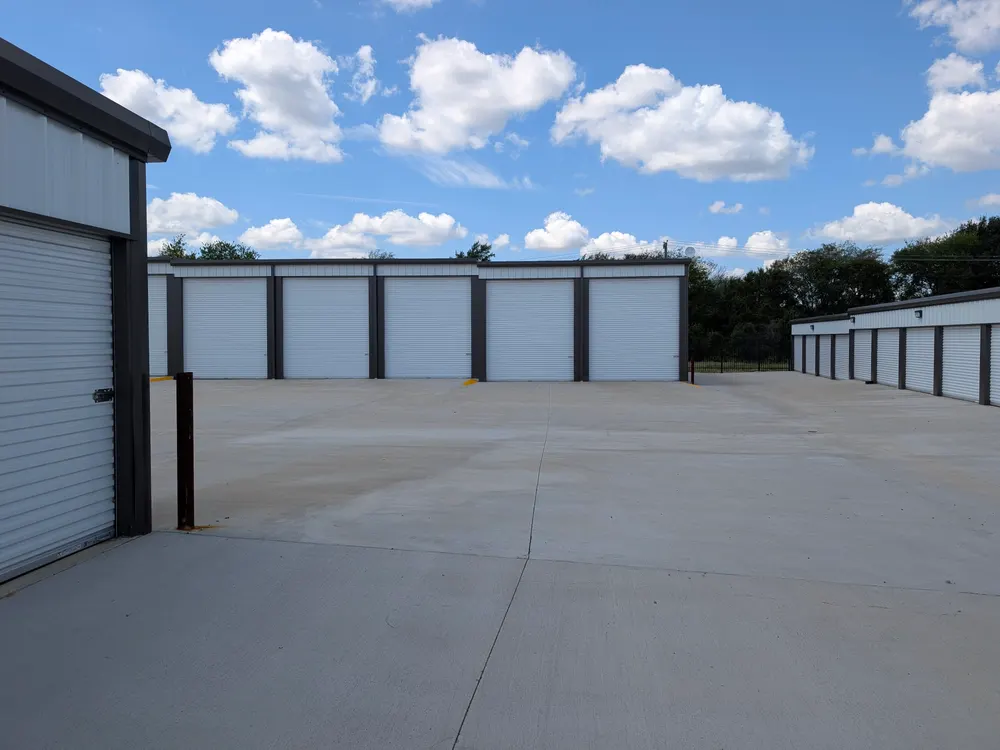
Drive-up unitsThe last three years absorbed a record wave of new storage. That wave is over. Deliveries are projected to fall roughly 60% from the 2023 peak, leaving an operator who already owns a new building with very few new neighbors.
2026 onward projected
Absorption now outpaces new deliveries in heavily built markets. In markets like Malakoff, an operator can push rate without new competition diluting demand.
Regional portfolios trade to institutional buyers at compressed cap rates: a 5% cap versus 6% is roughly 20% more value. Malakoff is underwritten across 6.25%, 6.00% and 5.75% exits on its own; a portfolio exit is upside, not the plan.
Lake-home and second-home ownership around Cedar Creek Lake drives seasonal and recreational storage, with the area’s estimated median home value nearly quadrupling over the last 20 years.
Grades rate the facility and its website separately. Inside five miles, the four closest competitors are 97.5% occupied, and only one offers climate control. Journey Malakoff adds 69,950 NRSF, roughly 1.5x all four combined. Seven of twelve competitors have no climate control, and the best facility in the trade area has no technology.
| # | Facility | Mi / Min | SF | Facility grade | Web grade |
|---|---|---|---|---|---|
| 1 | HunnyBear Storage96.6% occupied · no CC | 0.6 / 1 | 8,327 | D+ | C+ |
| 2 | McKamy Storage97.5% occupied · DU 100% full · only CC inside 5 mi | 3.5 / 5 | 17,000 | A− | B− |
| 3 | EZ Self Storage97% occupied · no CC | 4.1 / 6 | 15,000 | B− | C+ |
| 4 | Hwy 31 Storage100% occupied · no CC | 5.0 / 5 | 5,117 | C− | D− |
| 5 | Athens Climate StorageNicest competitor in trade area · CC · no technology | 6.6 / 7 | 15,000 | A− | B− |
| 6 | Athens Secure Storage & ParkingDecent units, gravel property · no CC | 6.9 / 8 | 14,000 | C+ | B− |
| 7 | Payne Springs Self StorageSold out of almost everything · no CC | 8.5 / 11 | 26,000 | B+ | B− |
| 8 | Lakeridge Self Storage Mabank95% occupied · CC | 9.2 / 16 | 10,000 | B− | B− |
| 9 | Athens Self StorageCC · no website at all | 10.4 / 13 | 12,000 | C− | F |
| 10 | Drop and Lock StorageNo online pricing or rentals · no CC | 10.4 / 14 | 22,000 | A− | D− |
| 11 | TSP AthensOnly drive-up units · no CC | 11.3 / 13 | 22,000 | B− | A− |
| 12 | Access StorageSold out of most sizes · CC | 17.4 / 25 | 15,000 | B− | B− |
Sampling of the most relevant competitors, not exhaustive. Pin fill = facility grade · ring = website grade · slashed badge = no climate control. CC = climate-controlled · DU = drive-up.
Bought below the developer's own cost to build, and roughly 17% below what the same facility would cost to replace today. Leased up, run on Journey's stack, sold stabilized.

Grow in-place revenue from $0.66 to $1.00 per SF per month, blended across all SF including parking.
Increase occupancy to 88%, stabilizing in Year 4.

Deploy $921,000 in capex and interest reserves, including a $493,690 construction budget.

Fast online rentals, seamless self service move-ins, convenient smart access under the JOURNEY.STORAGE™ brand.
A building bought empty does not cover its interest in year one. The $921,000 raised at close covers the gap while the loan is interest-only for 24 months. By Year 3 the property covers its debt 1.41 times over; Year 4 is stabilized at 1.26x after the refinance, and Year 5 reaches 1.41x. Read the negative Year 1 as a funded lease-up, not a surprise.
$5.96M over the $5.65M purchase price; $11.24M at 6.25% and $12.00M at 5.75%.
A 2.11x net multiple to Direct Equity Source investors.
Self-storage deals are typically underwritten at a 13 to 20% net IRR and a 1.5 to 2.5x equity multiple. Malakoff is projected at 20.76% and 2.11x net to Direct Equity Source investors at a 6.00% exit, with a basis discount that ground-up development cannot offer as downside cover.
| Tier | To LP | To GP | Note |
|---|---|---|---|
| 1 · Preferred return | 8.0% | 0% | Compounding, paid before any promote |
| 2 · Up to a 13% IRR | 80% | 20% | Sponsor promote begins |
| 3 · 13% to 15% IRR | 75% | 25% | Second promote tier |
| 4 · Above 15% IRR | 70% | 30% | Third promote tier |
The Manager’s 10% co-invest shares pro rata alongside investors.
| Exit cap | Sale price | Net IRR | Net multiple |
|---|---|---|---|
| 6.25% | $11.24M | 19.81% | 2.03x |
| 6.00% | $11.61M | 20.76% | 2.11x |
| 5.75% | $12.00M | 21.73% | 2.19x |
Returns are net to Direct Equity Source investors.
| Acquisition loan proceeds | $3,900,000 | 56.3% |
| LP equity | $2,722,275 | 39.3% |
| Manager equity (co-invest) | $302,475 | 4.4% |
| Total | $6,924,750 | 100% |
| Purchase price | $5,650,000 | 81.6% |
| CapEx & interest reserve | $921,000 | 13.3% |
| Sponsor fees (2% acq. + 2% guaranty) | $191,000 | 2.8% |
| Closing costs | $84,750 | 1.2% |
| Loan fees | $78,000 | 1.1% |
| Total | $6,924,750 | 100% |
| Year 1Lease-up | Year 2Lease-up | Year 3Lease-up | Year 4Stabilized | Year 5Stabilized | |
|---|---|---|---|---|---|
| Rental income | $186,476 | $470,290 | $703,910 | $917,922 | $1,005,045 |
| Ancillary income | $12,384 | $29,722 | $39,629 | $44,582 | $44,582 |
| Fee & other income | $13,169 | $19,773 | $25,550 | $30,745 | $33,333 |
| Bad debt | ($1,865) | ($4,703) | ($7,039) | ($9,179) | ($10,050) |
| Discounts | ($25,155) | ($21,500) | ($17,200) | ($12,900) | ($12,900) |
| Effective gross income | $185,009 | $493,581 | $744,850 | $971,170 | $1,060,009 |
| Total expenses | ($244,896) | ($260,729) | ($286,444) | ($310,562) | ($323,250) |
| Net operating income | ($59,887) | $232,852 | $458,407 | $660,608 | $736,759 |
| Yield on cost | (0.86%) | 3.36% | 6.62% | 9.54% | 10.64% |
| Debt service coverage | (0.23x) | 0.88x | 1.41x | 1.26x | 1.41x |
| Investor returns Net to Direct Equity Source investors · per $1M invested | |||||
| Annual return | $0 | $0 | $979,147 | $35,730 | $1,008,550 |
| Cumulative cash on cash | 0.00% | 0.00% | 97.91% | 101.49% | 202.34% |
Debt service is about $264k a year during the 24-month interest-only period. The projected cash shortfalls in Year 1 and Year 2 are covered by the $921k reserve raised at close; Year 4 and Year 5 coverage reflects the refinance. Investor returns are cash distributions to Direct Equity Source investors over the hold, based on a $1M investment; they are not derived from the operating lines above.
Sophisticated investors ask two questions before the returns: how much of the sponsor's own capital is in, and what the sponsor is paid regardless of outcome. Both answers are here, in the open.
The sponsor’s Manager entity co-invests 10% of the equity alongside investors, on the same terms. If the plan misses, the sponsor misses with you.
The Sponsor guarantees the $3,900,000 acquisition loan as required by the lender. LPs carry no recourse.
About 2.8% of total project cost: a 2% acquisition fee and a 2% loan guaranty fee, disclosed in the uses table.
Journey.Managed operates the property under the JOURNEY.STORAGE™ brand at 6% of gross revenue, with a $2,500 monthly minimum. The sponsor earns a 0.25% annual asset management fee on project cost and a 6% construction management fee on the construction budget. There is no disposition fee.
Your capital goes in through Direct Equity Source and DES pools commitments into a single SPV that holds one LP position in the Malakoff property, so you keep one relationship from first call to final distribution.
You commit capital to Direct Equity Source and deal with DES directly, from subscription to every distribution and report.
Pools investor commitments and holds a single LP position in the property entity. Passes distributions, K-1s and reporting through to you.
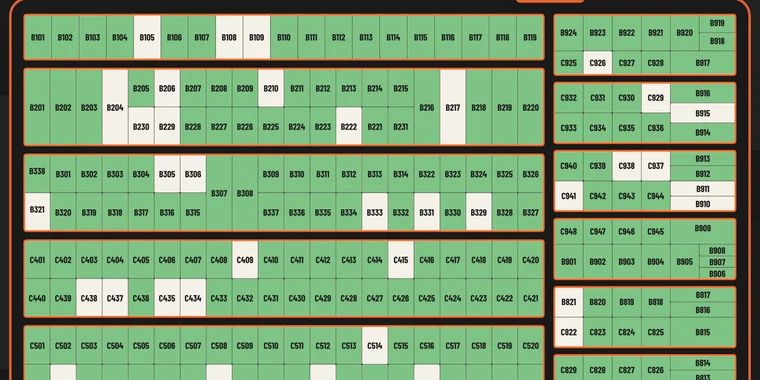
430 spaces on 5.37 acres. Operated by JOURNEY.STORAGE™, the vetted operating partner: lease-up, revenue management, technology and day-to-day asset management.
Structure shown for illustration. The SPV’s operating agreement and subscription documents govern; entity names are subject to final documents.
We do cost segregation. Ask about accelerated “bonus” depreciation.

Target closing is December 21, 2026. Documents on request through Direct Equity Source; commitments taken in order received.
← → navigate · M index · F full screen